Falling behind on a mortgage can make every letter and deadline feel urgent. If you are trying to understand how to stop foreclosure in Jacksonville, FL, the first step is to confirm where the case stands and contact your mortgage servicer as soon as possible. A HUD-approved housing counselor can also help you review options at no charge.
There is no single solution that works for every homeowner. Your loan type, missed-payment amount, equity, income, court deadlines, liens, and goals all matter. This guide explains the main paths so you can ask better questions and act before your choices narrow.
This article provides general information, not legal, credit, tax, or financial advice. If you have been served with a lawsuit or have a scheduled sale date, speak with a qualified Florida attorney promptly.
Start With These Three Steps
1. Confirm the foreclosure stage and important dates
Open every notice from the mortgage servicer and court. Write down the amount claimed due, the case number, any response deadline, and any scheduled hearing or sale date. Florida uses a judicial foreclosure process, so court papers and deadlines matter.
2. Contact the mortgage servicer
Ask for the loss-mitigation department and request the available application. The Consumer Financial Protection Bureau advises homeowners who are struggling with mortgage payments to contact the servicer promptly. Available programs vary by loan and servicer.
3. Contact a HUD-approved housing counselor
A HUD-approved counselor can help you understand your finances, review servicer options, and prepare for conversations with the mortgage company. Foreclosure-prevention counseling through a HUD-approved agency is available free of charge.
Options That May Help You Keep the Home
Loan modification
A loan modification changes one or more mortgage terms. It may change the interest rate, payment amount, loan term, or treatment of missed payments. Approval is not guaranteed, and the servicer will usually require financial documents and a complete application.
Forbearance or repayment plan
Forbearance may temporarily pause or reduce payments when the hardship is temporary. It does not erase the missed amounts. A repayment plan may spread arrears over future payments. Ask the servicer to explain the payment terms in writing and what happens when the temporary period ends.
Reinstatement or refinance
Reinstatement means bringing the loan current, including any permitted costs. Refinancing may be possible in limited situations, usually before the delinquency becomes severe and only if the homeowner qualifies for a new loan. A housing counselor can help you evaluate whether either path is realistic.
Bankruptcy consultation
Filing a bankruptcy petition generally triggers an automatic stay that stops many collection and foreclosure actions, but exceptions apply and a lender may ask the court for permission to continue. Bankruptcy has serious legal and financial consequences. Speak with a licensed bankruptcy attorney before treating it as a solution.
Options If You Need to Leave the Home
Traditional or direct sale
If the home is worth more than the mortgage balance and other amounts that must be paid at closing, selling may allow the loan to be paid off and any remaining proceeds to go to the seller. A traditional listing may pursue broader market exposure. A direct cash offer may trade some potential price for speed, an as-is sale, and fewer contingencies.
A sale does not stop a foreclosure merely because an offer is accepted. The transaction must close in time, the title company must confirm the payoff and liens, and the proceeds must be sufficient or otherwise approved. Court dates and lender actions should be verified throughout the process.
Short sale
If the mortgage and other required payoffs exceed the expected sale proceeds, a short sale may be considered. It requires lender approval and a complete loss-mitigation package. Sellers should understand the written terms, including how any remaining balance is treated and whether tax or legal questions require professional advice.
For a focused comparison, read Short Sale vs. Foreclosure in Florida.
Deed in lieu of foreclosure
A deed in lieu transfers ownership to the mortgage servicer instead of proceeding through a foreclosure sale. The servicer must approve it. Any release of the remaining debt should be confirmed in writing, and other liens can affect eligibility.
Avoid Foreclosure in Florida: Cash Sale vs. Loan Modification
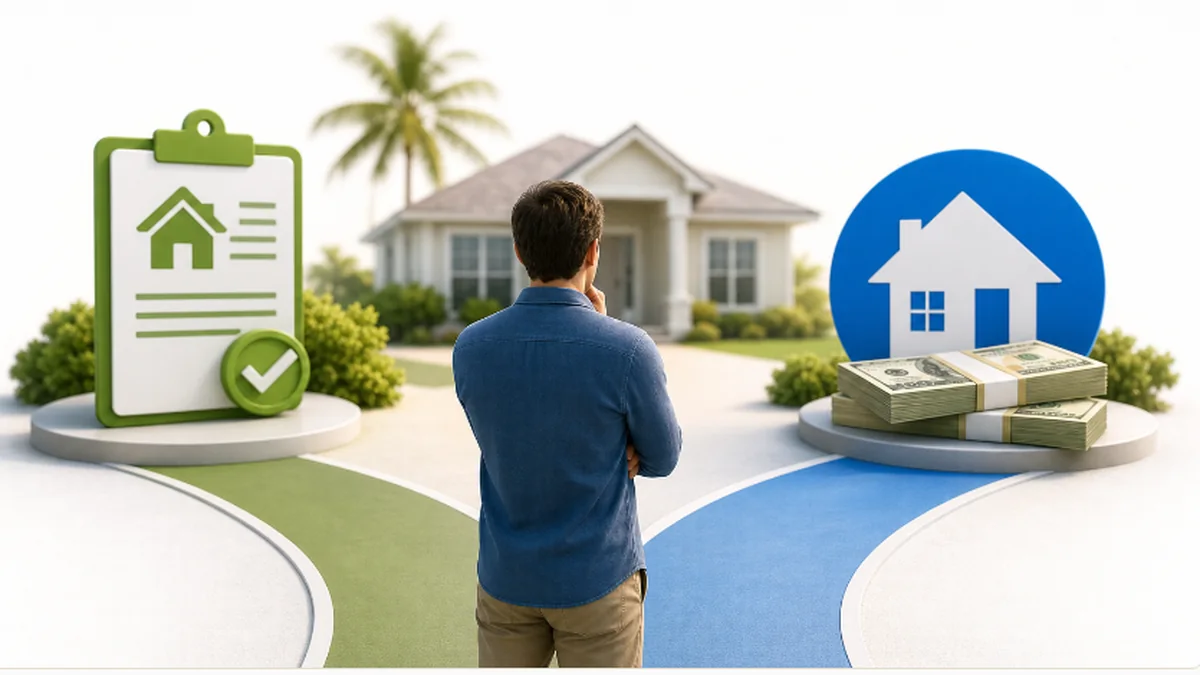
A loan modification and a direct cash sale solve different problems. A modification is meant to help you keep the house under changed mortgage terms. A direct sale is meant to transfer the property before a completed foreclosure sale, if the transaction can close and the payoff, title, liens, buyer performance, and court schedule all line up.
“A loan modification is a tool for keeping the house. If you do not want to keep it, or if keeping it is not financially realistic, a modification may not fit your goal.”
Jesse Wyatt, Synergy Buys Houses Jacksonville
Neither option is automatic. A loan-modification application does not guarantee approval. A signed purchase agreement does not stop a foreclosure by itself. Get important dates and decisions in writing, keep checking the court docket, and ask a qualified Florida attorney about case-specific legal questions.
Cash sale or loan modification: questions to compare before a Florida foreclosure sale
| Question | Direct cash sale | Loan modification |
|---|---|---|
| Main goal | Sell the property before a completed foreclosure sale, if the transaction can close in time. | Keep the property by seeking changed mortgage terms. |
| Who decides | The seller and buyer negotiate a contract. The title company, lienholders, servicer, and sometimes the court can affect whether closing can occur. | The mortgage servicer reviews the borrower and loan under its available programs. Approval is not automatic. |
| What must work | Title, payoff, liens, buyer funds, written conditions, and the court schedule must support closing. | The servicer needs the required documents and must determine which loss-mitigation options, if any, are available. |
| Main financial question | What will the seller receive after the mortgage payoff, liens, taxes, and agreed closing charges? | Is the proposed payment sustainable after insurance, taxes, utilities, maintenance, and other household costs? |
| Tradeoff | A direct offer may be below the possible value of a repaired, market-ready retail sale. | Revised terms may still be unaffordable, or the application may be denied. |
| What does not happen automatically | Signing an offer does not stop the foreclosure case. | Applying does not guarantee a pause or an approved modification. |
| May fit when | You do not want to keep the house, or keeping it is no longer financially realistic. | You want to keep the house and a workable modified payment may be available. |
When a loan modification may fit
A modification deserves serious attention when you want to stay and can realistically afford the proposed payment. The Consumer Financial Protection Bureau says homeowners who are struggling should contact the mortgage servicer promptly and complete the requested mortgage-assistance application. A HUD-approved housing counselor can also help you understand available options and organize the paperwork.
Ask the servicer to confirm whether the application is complete, what deadlines remain, and whether any foreclosure safeguard applies. Federal rules can create evaluation duties and other protections for a complete application received early enough, but those rules have conditions and exceptions. Do not treat a verbal update as proof that a scheduled sale has stopped.
Review the written proposal carefully. Confirm whether it is temporary or permanent, what the new payment will be, how past-due amounts are handled, and what must happen before the change becomes final. If the revised payment still does not work, compare selling options before the court schedule narrows further.
When a direct sale may fit
A direct sale may be worth comparing when you plan to move, the house needs work, or the payment is no longer sustainable. Start with a current mortgage payoff and a title review. Identify liens, property taxes, association balances, judgments, and other amounts that may need to be paid or resolved.
A real buyer should provide a written agreement that identifies the legal buyer, price, conditions, assignment language, and proposed closing date. Ask for proof of funds. Compare the offer with a realistic listing estimate and the likely net from each route. A direct offer can provide a simpler process, but it may be below the possible repaired, market-ready retail value.
If the expected sale proceeds will not cover the mortgage and other required amounts, the transaction may require lender approval as a short sale. Get any approval and treatment of a remaining balance in writing. Do not assume a shortage will be forgiven.
The deadline is controlled by the case, not a marketing promise
Florida uses a judicial foreclosure process. In Duval County, the Clerk says foreclosure case information can be reviewed through its CORE portal. If a final judgment sets a sale, the date in the court record controls. The Clerk also explains that a foreclosure sale, certificate of sale, objection period, and certificate of title are separate stages.
That is why timing must be checked against the actual docket. A proposed cash closing or pending modification review is not enough by itself. Continue communicating with the servicer and get case-specific legal advice if you have been served or a sale date is close.
For independent help, contact your mortgage servicer and use the CFPB housing-counselor locator. The CFPB also lists the HOPE Hotline at 888-995-HOPE (4673). Review the Duval County Clerk foreclosure guidance for local case and sale information.
If you want a written direct offer to compare with your lender’s proposal, request a no-obligation property review. Synergy may evaluate the property for a direct purchase. Any price, timing, conditions, and cost allocation will be stated in the written agreement.
This section provides general educational information. It is not legal, tax, credit, or financial advice.
How Selling During Foreclosure Works
A homeowner who still owns the property may be able to sell before the foreclosure sale, but the available time depends on the case. Start by obtaining a current mortgage payoff, identifying liens or judgments, confirming the court schedule, and choosing a sale method that fits the remaining time and property condition.
If you want a detailed explanation of listing, short sale, and direct-sale paths, read Selling a House in Foreclosure in Jacksonville.
Questions to Ask Before Accepting a Cash Offer
- Who is the legal buyer named in the written agreement?
- Is the offer subject to inspection, assignment, financing, or another contingency?
- Which seller costs, title charges, liens, or prorations will appear on the closing statement?
- What happens if the title company cannot clear the property before the scheduled sale?
- What is the estimated net amount after the mortgage payoff and other required charges?
- Can the buyer show proof of funds or explain the funding source?
Synergy Buys Houses Jacksonville is a direct local buyer serving Jacksonville and selected nearby Northeast Florida communities. We purchase some properties as-is. A direct offer is often below the price a repaired, market-ready property might achieve through a retail listing. The written offer and estimated closing statement should be reviewed before you decide.
Foreclosure Warning Signs to Avoid
- Anyone guaranteeing that they can stop the foreclosure regardless of the case facts.
- Pressure to sign over title or sign documents you do not understand.
- Large upfront charges for foreclosure-rescue help that a HUD-approved counselor may provide at no cost.
- A buyer or intermediary who will not identify the legal purchasing party or explain assignment terms.
- Verbal promises that are missing from the written agreement.
Frequently Asked Questions
Can I sell a Jacksonville house after receiving a foreclosure notice?
A sale may still be possible before the foreclosure sale if you hold title and the transaction can close in time. The payoff, liens, court schedule, buyer’s ability to perform, and title work all affect whether the sale can be completed.
Does accepting a cash offer stop foreclosure?
No. Accepting an offer does not by itself stop the case. A completed closing that satisfies the lender or an approved written agreement with the servicer may resolve the foreclosure, depending on the facts.
Will a sale erase missed payments from my credit history?
No seller or buyer should promise a specific credit result. Payment history and other account information may already have been reported. Review credit questions with the lender, a HUD-approved counselor, or another qualified professional.
What if the home is worth less than the mortgage balance?
A normal sale may not produce enough money to pay the loan and other required amounts. Ask the servicer about short-sale requirements and get any deficiency treatment in writing before closing.
What if an auction date is already scheduled?
Act immediately. Contact the servicer, a HUD-approved housing counselor, and a Florida attorney. A proposed sale should not be treated as complete until the title company confirms that closing can occur and the lender or court requirements have been addressed.
Where to Get Independent Help
- U.S. Department of Housing and Urban Development: Avoiding Foreclosure
- Consumer Financial Protection Bureau: Avoid Foreclosure
- CFPB: Find a HUD-Approved Housing Counselor
- Florida Statute 45.031: Judicial Sale Procedure
Request a Direct Offer
If selling is one of the options you are comparing, you can request a no-obligation offer from Synergy Buys Houses Jacksonville. We will review the property, explain how the offer was calculated, and let you decide whether the speed and as-is convenience are worth the trade-off against a possible retail sale.
Request a cash offer or call (904) 867-8673.